File
Local Telephone Service & Teletypewriter Exchange Service Tax Online with the
IRS-Authorized
Online Portal Simple720!
- User-friendly and streamlined filing interface
- Fast, secure, and IRS-compliant e-filing
- No installation or additional software needed
What is Local Telephone Service & Teletypewriter Exchange Service Tax(IRS Num 22)?
The Local Telephone Service and Teletypewriter Exchange Service Tax is a federal excise tax imposed under Section 4251 of the Internal Revenue Code (IRC) on amounts paid for local telephone service and teletypewriter exchange service. This tax falls under the Communications and Air Transportation Taxes category reported on Form 720 (Quarterly Federal Excise Tax Return).
- A 3 percent federal excise tax is imposed on amounts paid for local telephone service and teletypewriter exchange service.
- Local telephone service includes access to a local telephone system and the privilege of telephonic-quality communication with substantially all persons on that system, as well as related facilities or services.
- Teletypewriter exchange service is a communications service as defined in IRC Section 4251(b), historically applicable to teletype data services.
- The tax is imposed on the person paying for the service (the consumer).
- Service providers are responsible for collecting the tax from their customers and remitting it to the IRS.
- The tax applies to amounts paid for the communications service, excluding separate state/local taxes if separately stated on the bill.
Who Is Responsible for Paying the Local Telephone &
Teletypewriter Exchange Service Tax(IRS Num 22)?
The responsibility for paying the tax generally falls on:
-
 Customers/consumers who pay for local telephone and teletypewriter exchange services.
-
Service providers are responsible for collecting the tax
from their customers and remitting it to the IRS.
-
Service providers (telecommunications companies) must collect the tax on these services and report and remit it to the IRS on Form 720, Quarterly Federal Excise Tax Return in the period when the tax liability arises.
Local Telephone Service & Teletypewriter Exchange Service Tax Filing Requirements
| Category | Details |
|---|---|
| IRS Number | 22 (Local telephone service and teletypewriter exchange service Tax) |
| Reporting Section | Part 1 (Communications and Air Transportation Taxes) |
| Filing Frequency | Quarterly |
| Tax Rate | 3% of local telephone service charges |
| Tax Calculation Formula | Total taxable local telephone service charges × 3% |
| Details Required for Calculating the Tax Amount | Taxable local telephone service charges |
Local Telephone Service & Teletypewriter Exchange Service Tax Due Dates and Penalties
| Quarter | Tax Period Covered | Form 720 Due Date |
|---|---|---|
| Q1 | January 1 – March 31 | April 30 |
| Q2 | April 1 – June 30 | July 31 |
| Q3 | July 1 – September 30 | October 31 |
| Q4 | October 1 – December 31 | January 31 (following year) |
If you fail to file Form 720 for your excise tax on Local Telephone Service & Teletypewriter Exchange Service by the applicable due date, the IRS may impose penalties and interest . Common penalties include:

Generally 5% of the unpaid tax for each month or part of a month the return is late, up to 25%.

Generally 0.5% of the unpaid tax for each month or part of a month , up to 25%.

In case the taxes are unpaid, there will be an accrual of interest from the time when the taxes were due until the tax debt is settled.

There will be additional penalties where the federal tax deposits are late, insufficient, or deposited wrongly.
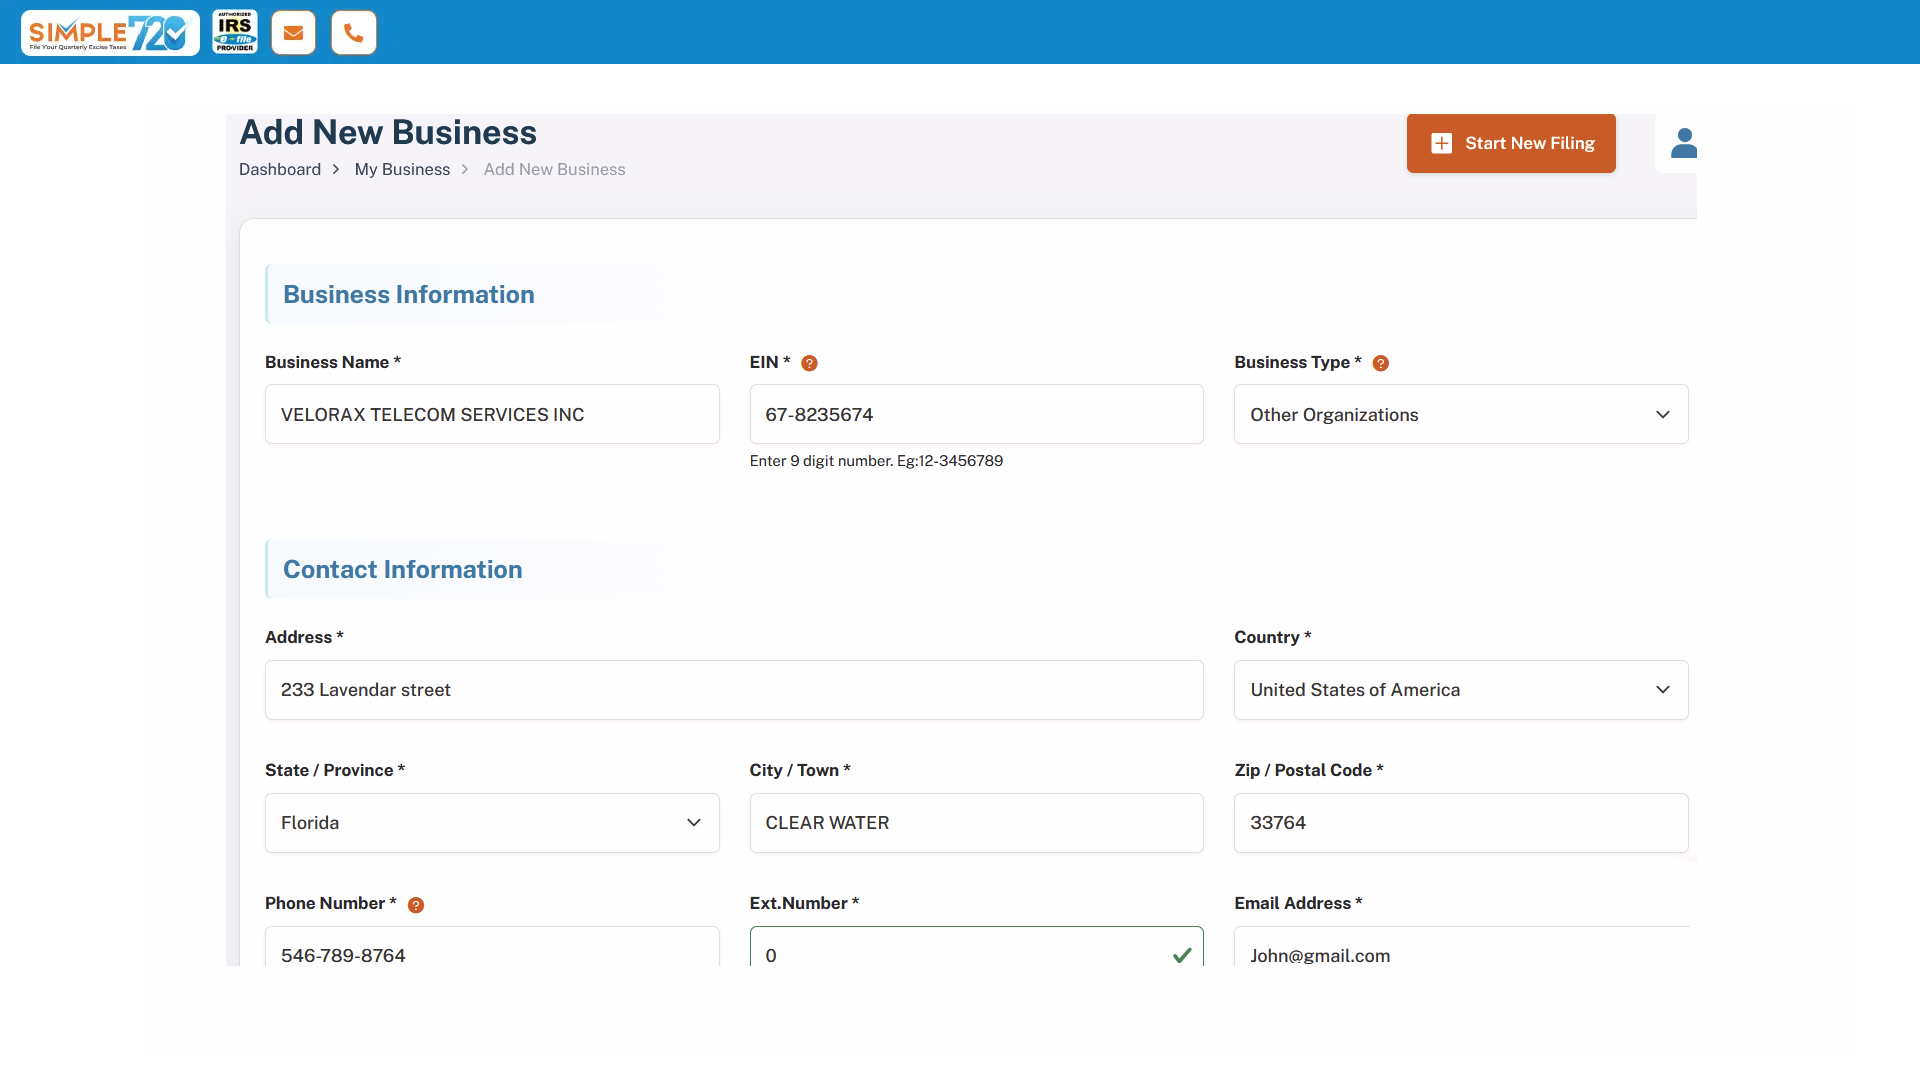
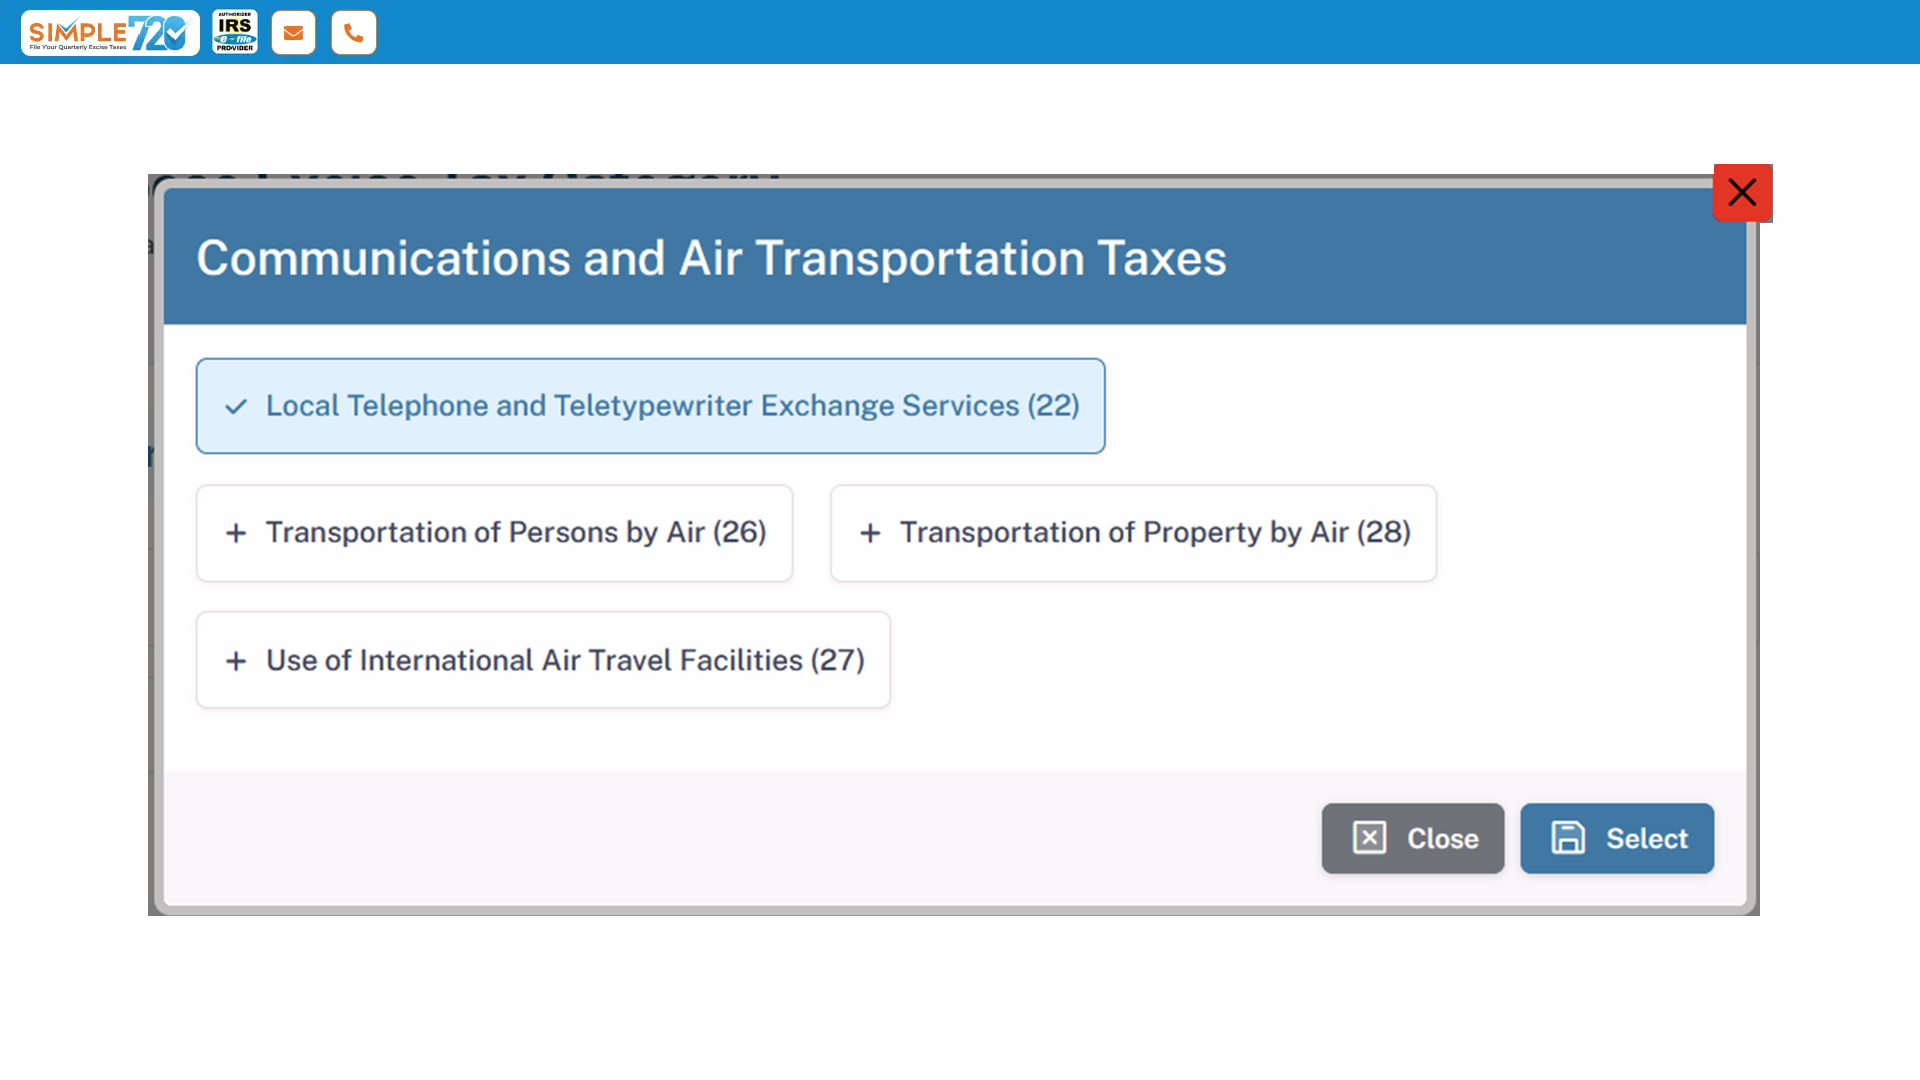
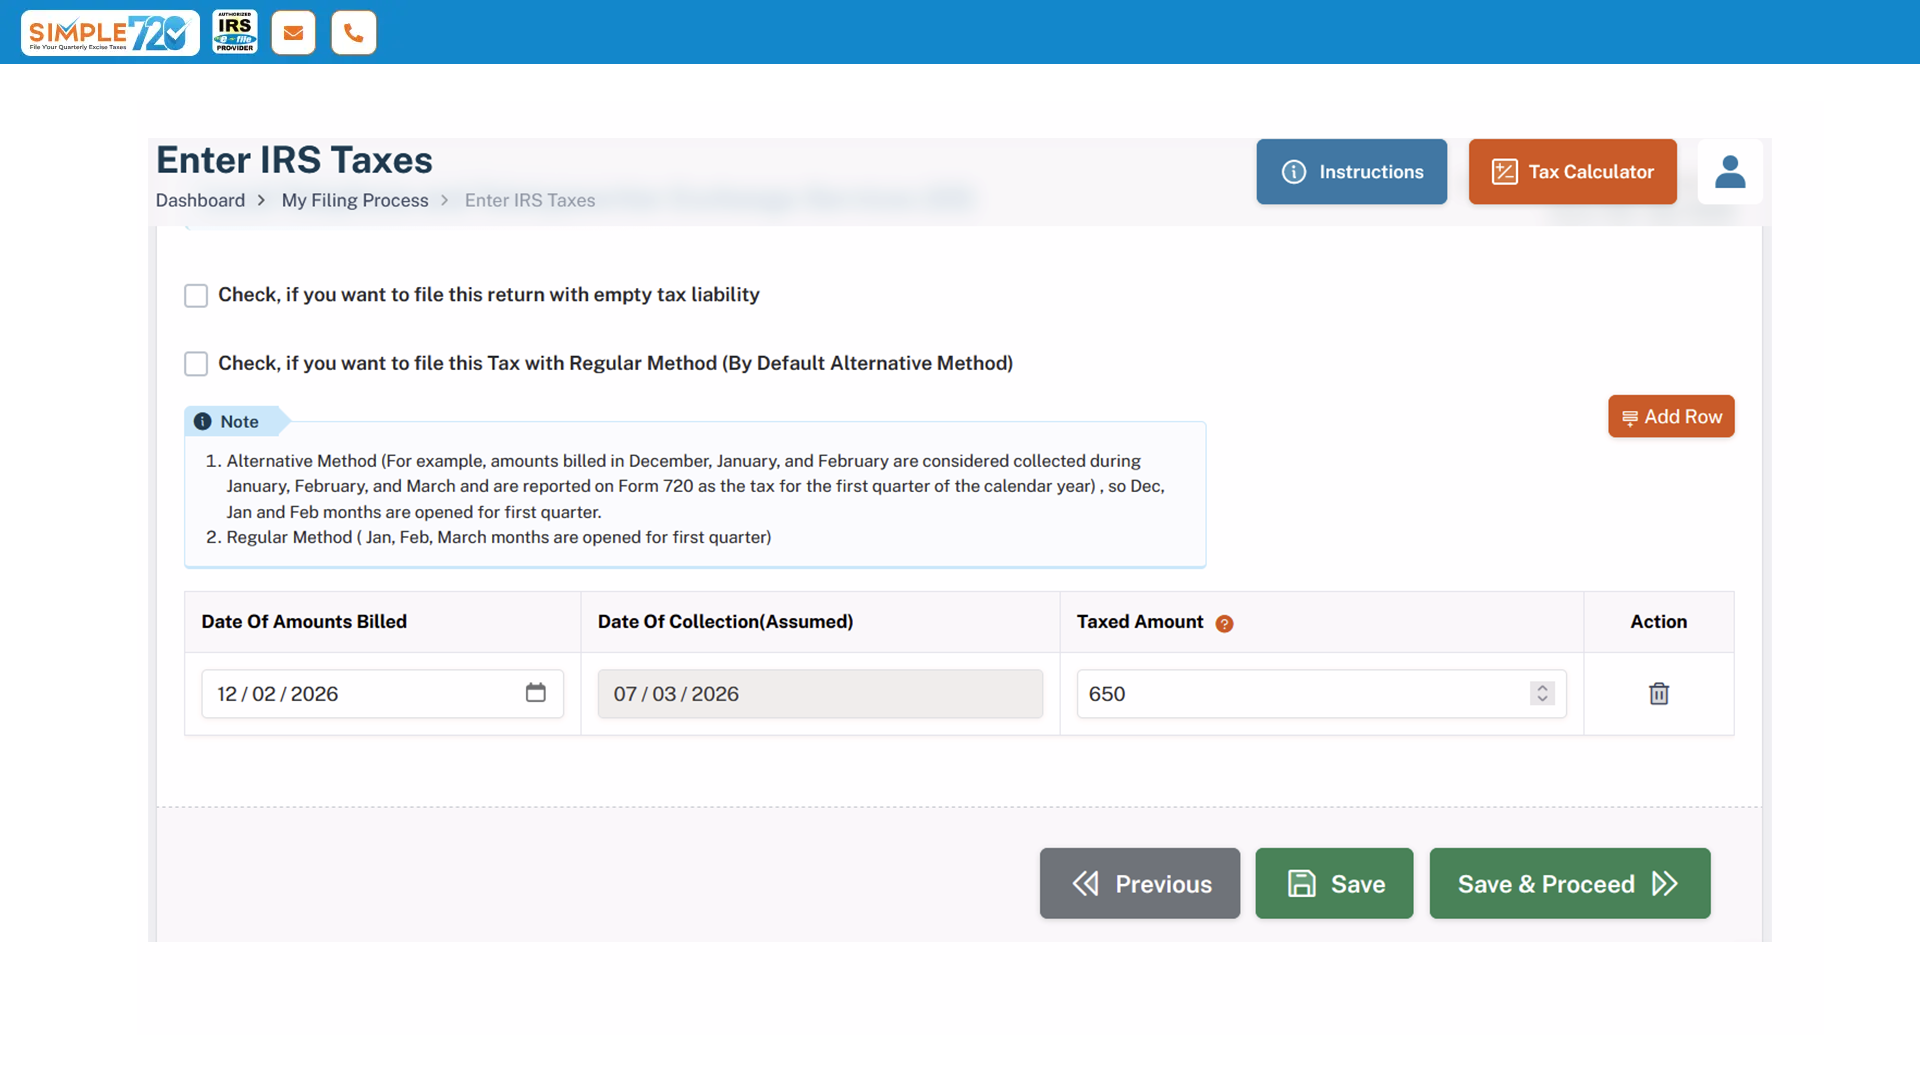
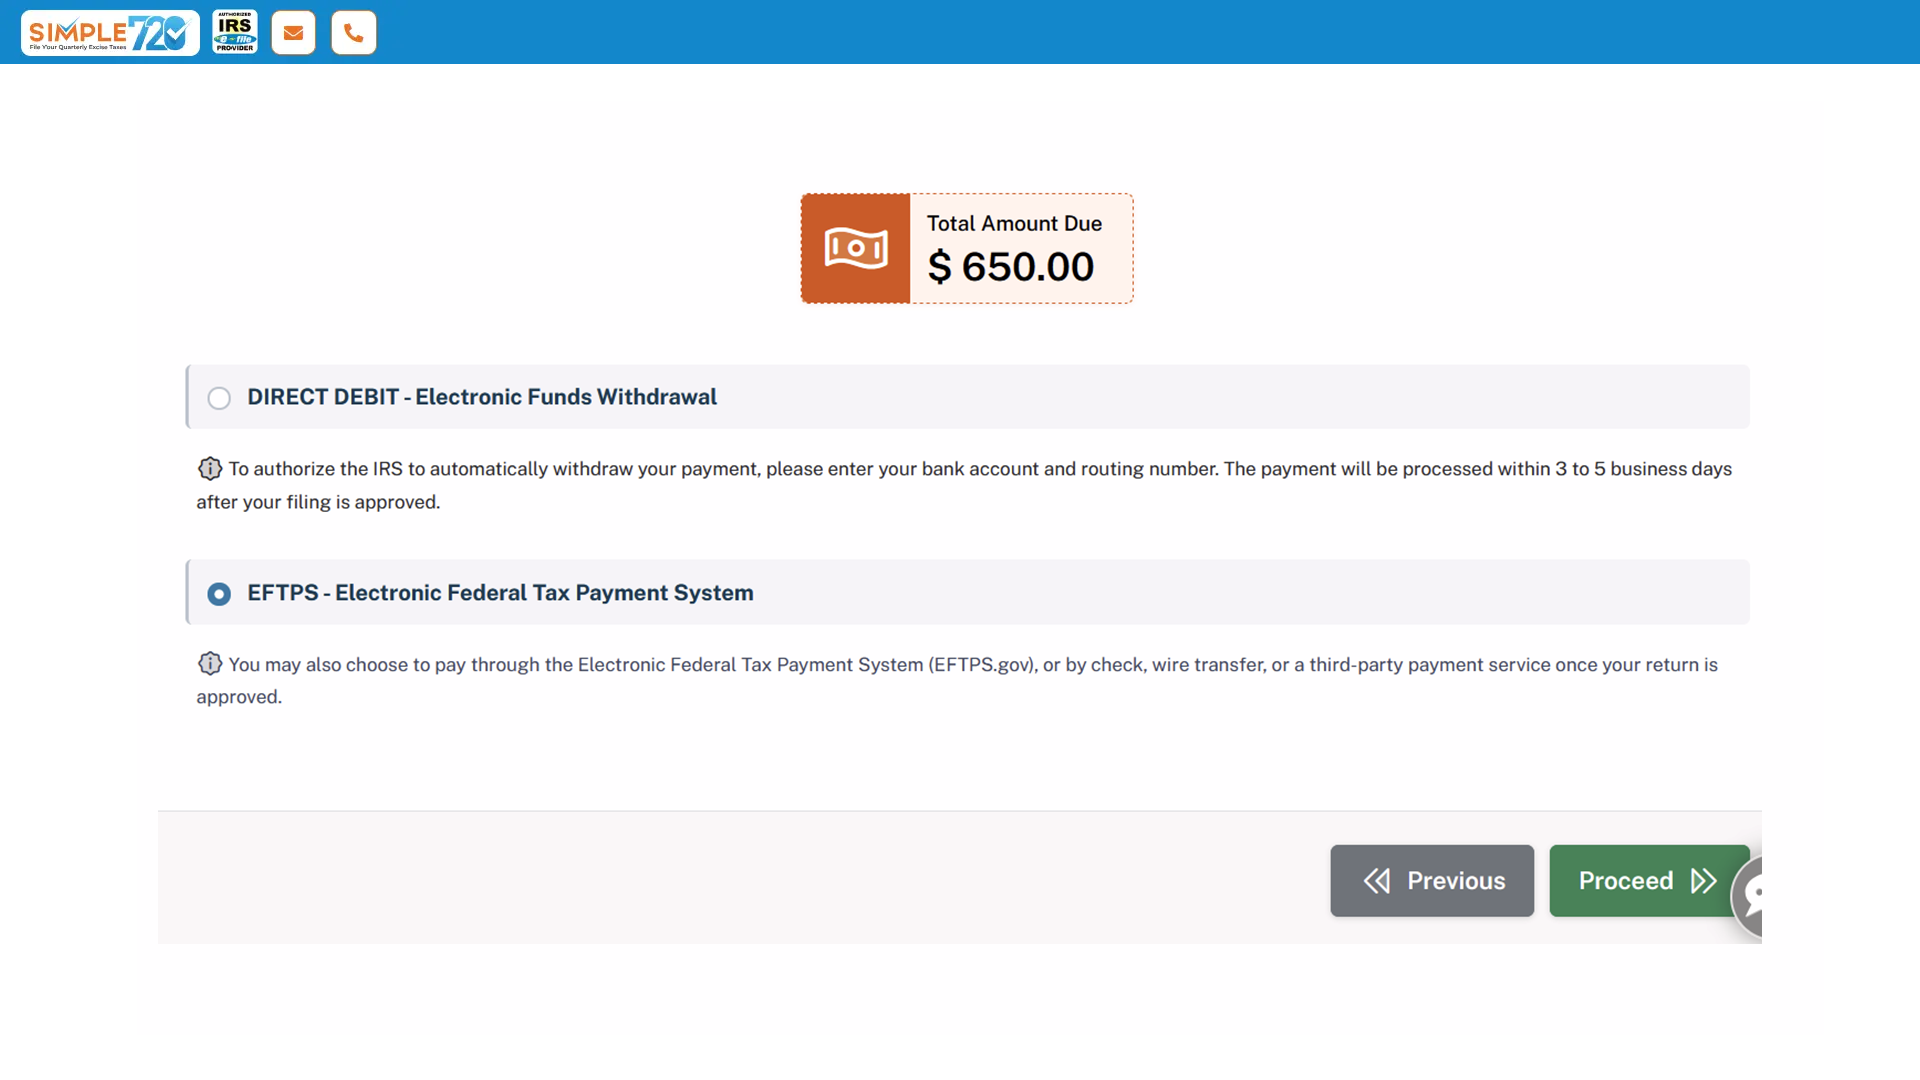
How to file Local Telephone Service and Teletypewriter Exchange Service Tax online with Simple720? (easy 4 Steps)
details
the Tax category
Tax details
your payment
Why Choose Simple720 for Filing Your Local Telephone Service and Teletypewriter Exchange Service Tax?
Simple720 vs Other Providers vs Manual Filing
| Filing Features | Simple720 | Other Providers | Paper Filing |
|---|---|---|---|
| Software Download | Not required | May be required | Not applicable |
| License | No license | May require license | Not applicable |
| Contract | No contract | May require contract | Not applicable |
| Cost | Affordable pricing | Often higher cost | Moderate |
| Filing Speed | Fast online filing | Varies by provider | Slower filing |
| Ease of Use | Simple guided process | Platform dependent | Complicated manual process |
| Efficiency | Highly efficient | Varies by provider | Less efficient |
| Tax Calculation | Automatic calculation | Provider dependent | Manual calculation |
| Support | Dedicated support | Limited support | No support |
| Overall Experience | Fast and simple | Varies by provider | More manual effort |
Effortless Filing for Local Telephone & Teletypewriter Exchange Service Tax Filing my Local Telephone & Teletypewriter Exchange Service Tax with Simple720 was simple and fast. The secure and IRS-compliant platform gave me peace of mind, knowing everything was filed correctly and on time.
Reliable and Secure Filing Platform I trusted Simple720 for filing my Local Telephone & Teletypewriter Exchange Service Tax, and I was not disappointed. The platform is secure, and the filing process was smooth and efficient, allowing me to file confidently.
Quick and Easy Filing Experience Thanks to Simple720's user-friendly interface, filing my tax was straightforward and fast. The step-by-step guidance made it easy to navigate, and I didn't have to worry about complicated paperwork.
Frequently Asked Questions
Want to learn more?
Request a free demo today!
Our experts are ready to assist you.
Book a Demo